Capital expenditure in key UK infrastructure sectors (water, rail, electricity transmission and distribution) is set to increase by 63%, rising from £103bn (2020–2025) to £169bn (2025–2030).
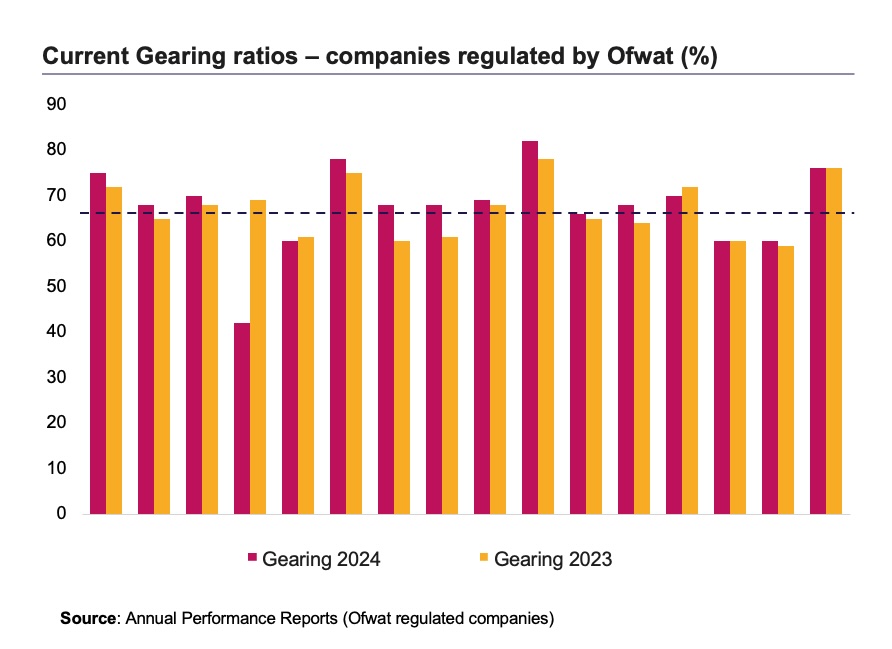
The marginal source of capital is equity because balance sheets are exhausted after many decades of debt finance. Leverage is particularly high in the water sector in particular is highly leveraged, with net debt reaching £69bn and gearing ratio averaging 70%, limiting its ability to raise further debt.
Equity investment needs thus face a step-change, increasing by over £120bn in water, rail, electricity transmission, and electricity distribution alone. Without sufficient investment, there is a risk of underfunding critical projects, leading to long-term service quality issues, failure to decarbonize the energy system, and increased consumer costs resulting from deteriorating asset health.
Projection: more than 63% capex growth, from £103bn in 2020–2025 to £169bn in 2025–2030
Cumulative capex, £bn (2023 prices)
- Electricity Transmission
- Electricity Distribution
- Rail
- Water and Wastewater
Period
Show the data as a table
| Period | Electricity Transmission | Electricity Distribution | Rail | Water and Wastewater |
|---|---|---|---|---|
| 2020–2025 | £7bn | £11bn | £55bn | £29bn |
| 2025–2030 | £33bn | £13bn | £63bn | £60bn |
Balance sheets are fully leveraged in water
In the past 20 years, debt has been the marginal source of finance in many regulated infrastructure sectors. As a result, companies, particularly in the water sector, are highly geared. Net debt across water companies currently stands at ~£69 billion, with gearing ratios averaging ~70%.
To finance capital projects, companies must raise new equity. This is particularly challenging in today’s environment due to high interest rates and international competition for capital. Is the current regulatory framework fit to support these investment decisions?
Sources
- Capex by sector (£103bn in 2020–2025 and £169bn in 2025–2030, 2023 prices): as printed on the chart, Electricity Transmission: Ofgem RFPRs and RIIO-T3 Business Plans; Electricity Distribution: Ofgem RFPRs and DESNZ, Appendix I: Electricity Networks Modelling; Water: APRs and PR24 FD; Rail: Annual Reports (Network Rail and HS2 Ltd.) and NIC, 2nd National Infrastructure Assessment.
- Gearing ratios of companies regulated by Ofwat: Annual Performance Reports (Ofwat regulated companies), as printed on the chart.